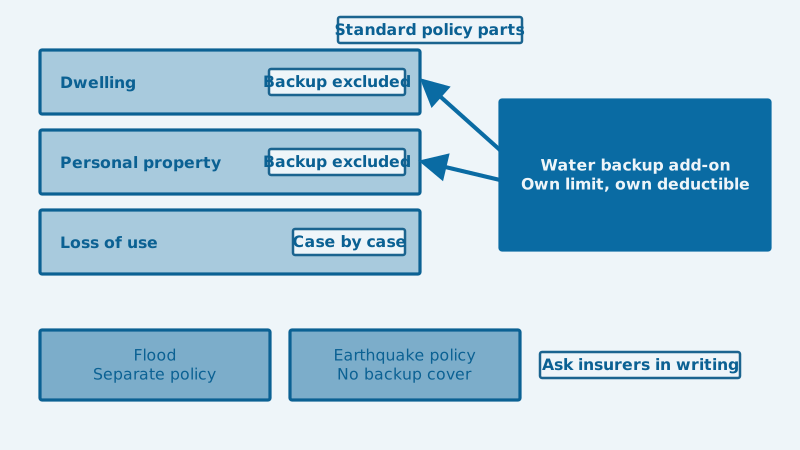
Most standard California homeowners policies do not pay for damage from a sewer backup. Backup coverage is usually an optional endorsement, an add-on you request and pay for. We are a plumbing service, not an insurer, so treat this as background and check your own policy wording. For the plumbing cause, see main line drain cleaning.
Does a standard homeowners policy cover sewer backup?
Generally no. The California Department of Insurance lists sudden and accidental water damage as a covered peril, and lists seepage, leaks, flood, mold and wear and tear among the things generally not covered. Sewer backup is not named on that page, so ask your insurer directly. Many policies exclude it unless an endorsement adds it.
The state's guides do not spell out a sewer backup rule, so the answer sits in your own contract. Look for the exclusions section and for words such as "water or sewage that backs up through sewers or drains." If that wording is there, the base policy will not pay for a main sewer line backup. If it says the policy covers backup up to a limit, you have an endorsement or a policy that includes it.
How is a homeowners policy built, and where does sewer backup fit?
A policy has parts: dwelling for the structure, other structures, personal property, loss of use for extra living costs, and liability. Each part covers named perils, minus exclusions, up to a limit, with a deductible. Sewer backup sits in the exclusions unless an endorsement moves it into coverage for specific parts, with limits and deductibles that vary by insurer. Ask for both in writing.
That is why two homes with the same insurer can get different answers. One might have a backup endorsement and one might have none. In general:
| Policy part | What it normally covers | Sewer backup, typical position |
|---|---|---|
| Dwelling | Walls, floors, built-in fixtures | Excluded unless endorsed |
| Personal property | Furniture, clothes, electronics | Excluded unless endorsed |
| Loss of use | Hotel and extra living costs when the home is unfit | Depends on whether the loss is covered |
| Endorsement for water backup | Damage inside the home from backup | Limit and deductible vary by insurer |
We cannot give you the limits of any policy, and we are not naming insurers. An agent or the insurer can show you your declarations page.
What is a water backup endorsement?
It is an optional add-on to a homeowners policy that covers damage from water or sewage that backs up through sewers or drains, It may carry its own limit and deductible, which vary by insurer, so ask for both in writing. It generally pays for damage inside the home, not for fixing the pipe.
The California Department of Insurance advises you to ask your agent about endorsements that extend coverage, and to read your policy when it arrives and again at renewal. Things to ask about your endorsement:
- What is the limit, and does it apply to the dwelling and personal property together?
- Is there a separate deductible?
- Does it cover cleanup and drying, or only repairs?
- Does it cover a backup caused by a clogged lateral on my own property?
- Are there waiting periods, or conditions on maintenance?
Cost varies by insurer and home. We do not have an official figure, so ask for a quote.
Does flood or earthquake insurance cover a sewer backup?
Not as a rule. Homeowners policies exclude flood, and flood needs separate coverage through the National Flood Insurance Program or a private insurer. The California Department of Insurance also notes that earthquake insurance does not cover water damage from outside the home, such as a sewer or drain backup.
That leaves a gap people miss. Rain can overload sewers, and a backup after heavy rain may fall between a flood policy and a homeowners policy. Wording differs, so ask each insurer in writing which cause it treats as a flood and which as a backup. Our page on basement sewer backup covers where homes are most exposed.
Does it matter whether the city or my own pipe caused the backup?
It can matter to a claim, and it matters to who pays for the pipe. In the City of Los Angeles, the owner maintains the private sewer lateral up to the connection at the city main, including the part under the street. A backup caused by a city main failure raises a different question than one caused by roots in your lateral.
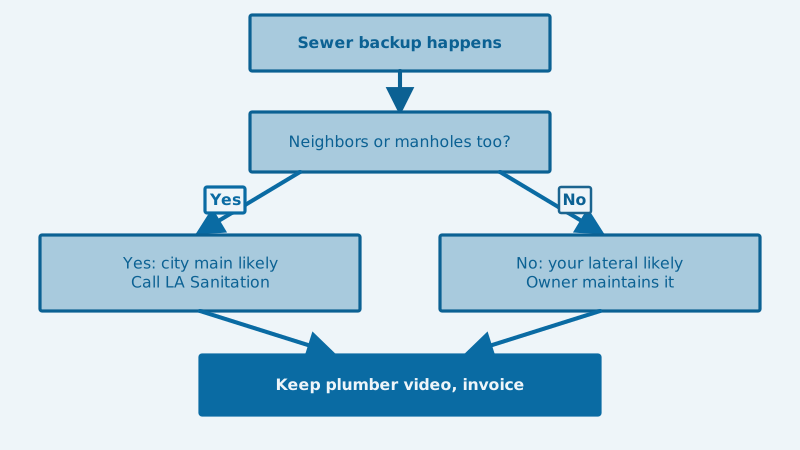
LA Sanitation's Customer Care Center, 1-800-773-2489, is open 24 hours a day. If neighbors are affected or manholes are overflowing, report it. If you think the city main is at fault, ask LA Sanitation how to file a claim, and keep the plumber's video and invoice. Do not assume either party is liable, because the facts decide.
What should I do after a sewer backup to protect an insurance claim?
Stop the source, photograph and video everything before you move it, keep receipts for emergency work, and call your insurer or agent promptly. The California Department of Insurance advises documenting the loss and protecting your property from further damage. Photograph damaged items before you discard them, and ask your insurer what it needs to see.
A short list:
- Have a plumber clear the line and keep the invoice and any camera video.
- Photograph the damage, including water lines on walls and soaked items.
- List what was damaged with approximate values.
- Keep receipts for cleanup, hotel stays and temporary repairs.
- If a claim is denied, ask the adjuster to cite the policy language they rely on. California requires a denial to be in writing with the reasons stated.
Our guide to cleaning up a sewer backup covers the physical steps in order. If you need the plumbing side, request a written price. Our home page lists what else we arrange.
Questions people ask
Does homeowner insurance cover the pipe that caused the backup?
Generally no. A backup endorsement, if you have one, usually pays for damage inside the home, not for repairing or replacing the pipe. Pipe damage from wear, roots and age is often excluded. Read the wording, or ask your insurer which parts of the lateral, if any, are covered.
Is sewer backup coverage required in California?
We have not found a state rule that requires insurers to offer it, and homeowners are not required to buy it. Check with the California Department of Insurance or your agent. What you can do is read your policy and ask for the endorsement if you want it.
What is a typical limit for sewer backup coverage?
It varies by insurer and policy. We do not have an official figure. Ask your agent for the limit in writing, and compare it with a written cleanup quote for your own home. A limit lower than that quote is worth knowing before a backup, not after.
Can I add sewer backup coverage after a backup happens?
Not for that loss. Coverage starts when the endorsement takes effect, so adding it after a backup will not cover the one that already happened. If you want protection, ask about the endorsement before the next rainy season. A new endorsement can also carry waiting rules, so read it.
Sources used
Page updated